Reading the Reverse: A Supplier Finance Disclosure Test for UK Analysts
Supplier finance has moved from the margins of working-capital management to a disclosure issue that UK equity analysts cannot afford to skim. The arrangements are commercially legitimate: a bank or intermediary pays a supplier earlier, while the buyer settles later. But the accounting presentation can obscure economic substance. When a company extends payment terms through a supplier finance programme, the cash-flow statement may show a benefit that is not a durable operating improvement. For analysts covering UK plc, the task is not to treat supplier finance as inherently aggressive. It is to test whether the disclosures allow a clean read of cash generation, leverage and liquidity.
Why the cash-flow statement deserves scrutiny
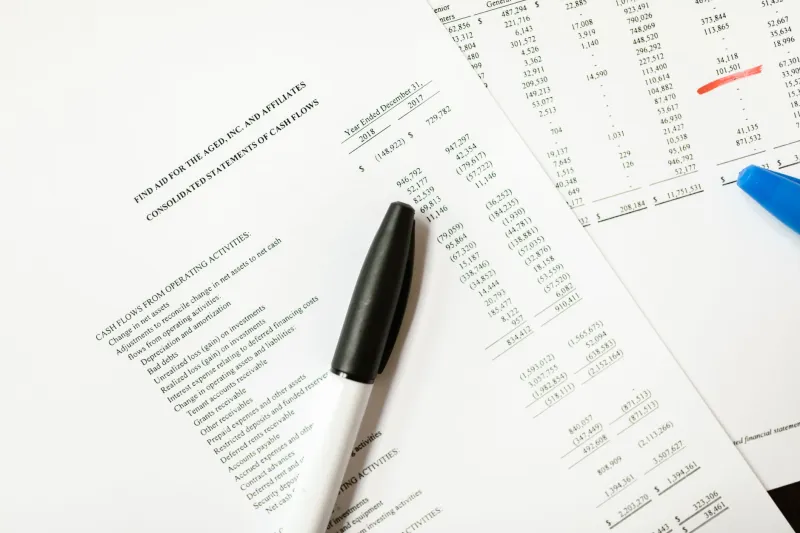
Operating cash flow is often used as a quality signal. It sits behind dividend cover, debt reduction and the credibility of management guidance. Supplier finance can convert what is economically a financing inflow into an operating cash-flow benefit, because the payable remains within operating working capital until settlement. If the programme grows, reported operating cash flow can improve even when underlying trading has not. If the programme is curtailed, the reverse can happen sharply.
That matters for UK analysts because many industrial, retail and consumer groups use supplier finance as a routine treasury tool. The question is not whether the tool exists. The question is whether the annual report gives enough information to judge its size, terms and direction of travel.
The disclosure baseline
The IAS 7 amendments on supplier finance arrangements require entities to disclose the terms and conditions of the arrangements, the carrying amount of related liabilities, the range of payment due dates, and non-cash changes in those liabilities. UK listed groups should provide this in the annual report, although interim disclosures can be thinner. Analysts should start by locating the supplier finance note, then cross-check it against the balance sheet, the cash-flow statement and the notes on financial liabilities.
A useful first test is consistency. Does the carrying amount in the supplier finance note reconcile to a line item elsewhere in the accounts? Is the liability presented within trade payables, within other financial liabilities or within borrowings? Has the classification changed year on year? Without that reconciliation, the disclosure is a description rather than an analytical tool.
A six-point analyst checklist
1. Map the arrangements, not the label
Companies use different labels: reverse factoring, supply-chain finance, confirmed payables and supplier payable programmes. Do not rely on the label. Read the description of who initiates the arrangement, whether suppliers can opt in, whether the buyer guarantees payment, and whether the bank has recourse to the supplier or the buyer. A programme that is economically close to borrowing should be treated as such in credit analysis, even if it sits within trade payables.
2. Reconcile the liability to the cash-flow narrative
Compare opening and closing carrying amounts and identify non-cash movements. If the supplier finance liability grows while operating cash flow improves, ask how much of the improvement is financing rather than trading. The cash-flow statement may not show the programme separately, so the note becomes the bridge between the balance sheet and the operating cash-flow line.
3. Recalculate day counts with consistency
Days payable outstanding is usually calculated as trade payables divided by cost of sales, multiplied by 365. But supplier finance liabilities may sit outside trade payables, or within them alongside ordinary payables. Build a consistent definition across years and peers. If the company reports a supplier finance liability separately, test DPO both including and excluding it. A widening gap between the two measures is a signal worth pursuing.
4. Compare peers and trend, not just levels
Peer comparison is useful only when the accounting treatment is comparable. A retailer with a large supplier base may legitimately have longer payment terms than a specialist engineer. Focus on direction of travel: has the supplier finance liability grown faster than revenue or cost of sales? Has the disclosed range of payment due dates lengthened? Has the company changed banks or programme structure? These questions often reveal more than a single year-end ratio.
5. Test the balance-sheet classification and covenants
Check whether the liability is included in net debt and whether covenant definitions adjust for it. Rating agency treatments can differ, so read the debt note and the covenant disclosures. If supplier finance is excluded from net debt but is economically debt-like, leverage may be understated. Analysts should also consider how a sudden withdrawal of the programme would affect liquidity headroom.
6. Read the governance trail
Audit committee reports, key audit matters and auditor commentary can provide context that the notes omit. Look for language on supplier finance controls, payment practices or working-capital initiatives. The UK regulatory backdrop, including FRC scrutiny of cash-flow disclosures, gives analysts a legitimate reason to ask detailed questions.
Red flags for the next reporting season
Several patterns should prompt closer work. A generic description that does not explain the arrangement is one. A carrying amount disclosed without a range of payment due dates is another. So is an operating cash-flow uplift that coincides with a rising supplier finance liability but no discussion of financing effects. A change in classification without explanation, or a programme introduced near year-end, also merits scrutiny.
Questions to put to management
Ask what proportion of year-end trade payables is subject to supplier finance. Ask whether the programme has been extended, renewed or terminated. Ask how programme fees are accounted for and whether they are included in cost of sales or finance costs. Ask what would happen to operating cash flow if the programme were unwound. Finally, ask whether the board and audit committee treat the liability as debt-like for internal monitoring.
Conclusion
Supplier finance is neither good nor bad in itself. The mirage appears when disclosure lags commercial reality. A disciplined checklist helps UK analysts separate genuine working-capital efficiency from a financing tailwind, and it improves the quality of questions put to management. Before the next reporting season, the reverse factoring note should be read as a cash-flow document, a balance-sheet document and a governance document at the same time.